One Purchase, Two Lives: The Case For — and Against — the Flex Property
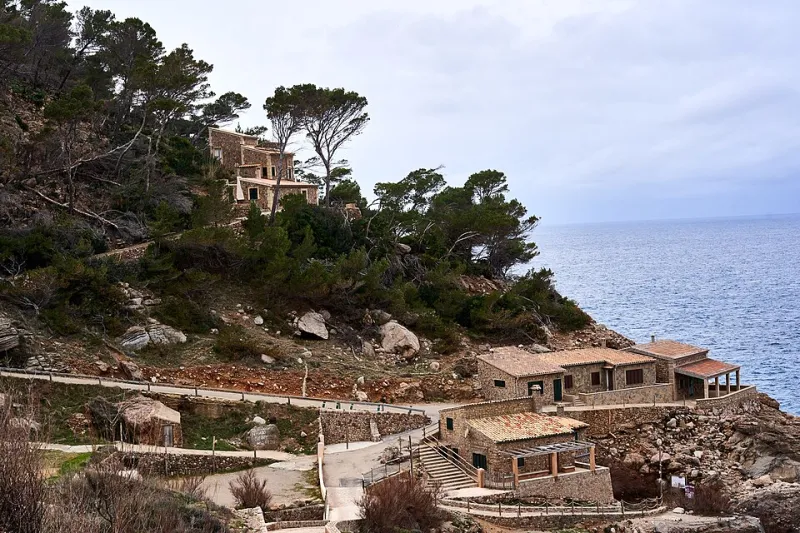
Photo: Graeme Churchard, CC BY 2.0, via Wikimedia Commons
There is a particular kind of buyer showing up in markets from the Outer Banks to the Arizona high country. They are in their late forties or fifties. They are not looking for a rental empire, and they are not ready to retire. They want a house that can do two jobs at once: a place to spend spring break and long summers now, and a home to settle into permanently a decade or more from now.
Call it the flex property. As an opinion, this publication believes the strategy is genuinely sound — but only for a narrow band of buyers, and only when it is planned with unusual discipline.
The Appeal Is Real
The logic is seductive. Rather than watching vacation rental income flow to someone else, you build equity in a place you love while using it on your own terms. Rental revenue in strong destination markets can cover a meaningful share of the mortgage. And when retirement arrives, you already know the town, the neighbors, the grocery stores, and the rhythm of the seasons — knowledge no relocation guide can provide.
There is also a hedge built into the strategy. Retirement destinations are volatile; the charming town you adore on vacation may feel different in February, or after ten years of growth. Living in a place part-time before committing to it full-time is the single best due diligence available.
The Math Demands Honesty
Now the caveats. Financing a second home typically means higher rates and stricter qualification than a primary residence, and lenders scrutinize occupancy intent closely. Insurance in coastal and wildfire-prone regions has become punishing. Short-term rental regulations can change with a single town council vote, and a property that underwrites beautifully on projected Airbnb income can be stranded overnight by a new permitting cap.
Tax treatment adds another layer. A home rented for more than fourteen days per year is treated differently from a pure personal residence, and the rules governing how many days of personal use are permitted before rental deductions are limited are unforgiving. Buyers who drift between personal use and rental use without records routinely leave money on the table or create compliance problems. A tax professional belongs in the conversation before the offer, not after the closing.
The Ten-Year Test
Here is the dividing line, in our view: the flex property works for buyers who can honestly answer yes to all three of these questions. First, could you carry the mortgage for twelve months with zero rental income? Second, do you genuinely intend to retire in this area, or is that a story you are telling yourself to justify the purchase? Third, will you hold the property for at least a decade, through market cycles, insurance renewals, and regulation changes?
If any answer is no, you are not buying a flex property. You are buying a vacation home with a retirement fantasy attached — an expensive indulgence, not a plan.
Buy the Life, Not the Listing
The buyers who succeed with this strategy tend to be unromantic about the process. They rent in the area for a full winter before buying. They model expenses conservatively. They choose locations with diversified economies rather than single-industry resort towns. And they work with local agents who will tell them the truth about a market's off-season.
A flex property, done well, is not a compromise between a vacation home and a retirement plan. It is a long, deliberate rehearsal for the life you intend to live. Approach it that way, and it can be one of the most rewarding purchases you ever make. Approach it as a shortcut, and it becomes a mortgage on a memory.